
Many of us plan to keep working in our current occupations until the average retirement age, which Empower puts at 63 for women and 65 for men. But Allianz found that 42% of Americans had to retire early for reasons they had no control over. For people in high-risk or high-stress occupations, the possibility of an early retirement is especially high.
The physical and mental toll of these jobs makes financial independence a priority. Since retirement can be unexpected, you’ll need to save up during your peak years and plan for life after your current career. But how do you get started and when? Here, I’ll show you how to identify your risks and take steps to become financially independent working in a high-risk job.
Look Hard at Your Job’s Risks
Before getting into financial independence planning, you need to carefully consider the risks for your high-risk occupation. For some of these jobs, the risks are mainly physical. Others are stressful and mentally demanding. Looking at these risks helps you figure out a possible retirement timeline. You’ll also better know how much to save.
If you’re a professional athlete, an injury could mean the end early on. And even if you don’t get hurt, performance issues from aging could force you out. According to Significance, the average athlete retired at just age 32. That gives you a potentially very short timeframe to save money and figure out a career transition plan. Saving aggressively early will be a must.
Tradespeople can often work even into their 50s or early 60s. But their work is much more hazardous. Not only do tradespeople often get injured, but the BLS also says that fatalities are high for this occupation. Then there’s the fact that doing physically demanding work gets harder as you get older. Even if you don’t quit tradeswork entirely, financial independence is important.
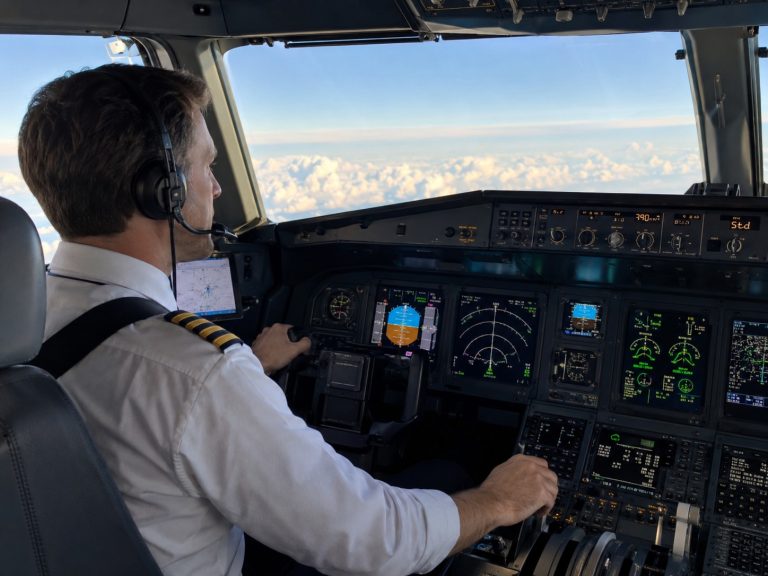
Then you have high-stress occupations like doctor, pilot, air traffic controller, and firefighter. These are mentally demanding since you’re responsible for people’s lives. It’s no surprise that burnout is high and many leave early. Keeping such jobs also requires staying healthy. Even a non-work injury or health issue could force you into retirement early. Plus, some jobs actually force early retirement. For air traffic controllers, that’s usually age 56.
Start Managing Money Wisely Now
Those risks I just mentioned make it important to get a handle on managing money before getting deeper into your financial independence plan. Give yourself a strong foundation by:
- Saving at least six months’ worth of expenses in an emergency fund, which is larger than the three-month minimum for other professionals.
- Make a budget realistic for your situation, including any varying income (if self-employed or seasonal) and expenses.
- Don’t start spending more just because your high-stress job starts paying you more; that’s the lifestyle inflation trap.
- Avoid debt, which will make it harder to save aggressively; pay it down before early retirement if you already have debt.
If you need some guidance on these steps, you’re not alone. Corebridge Financial found that 62% of Americans consider themselves to be beginners in finance. You can check some of our other articles to learn more about lifestyle inflation, common financial mistakes, budgeting, and emergency funds.
Consider Private Disability Protection
Disability is the biggest concern for high-risk occupations, especially physical ones. If you’re lucky, the injury doesn’t last long, and you return to your usual work with just a few restrictions. But others can put you out of high-risk work for years or permanently. While workers’ compensation can help here in some situations, you need to consider disability insurance.
If you’re an employee, you might already have this insurance. But it might not be enough to replace your income. Many high-risk professionals are in a different position. They work for themselves and don’t get this coverage from an employer. Private disability insurance can help out in both situations.
It’s often smart to get both short- and long-term disability coverage. That covers the annoying temporary issues and the more serious long-term ones. Another thing to look for is own-occupation coverage. That kind of policy pays out if you can’t do your specific high-risk occupation. Otherwise, insurers might only pay out if you can’t do any job. Always check the rules.
One catch is private disability insurance usually won’t replace all your income. Guardian says that these policies often replace up to 80% of it. The ones I considered for my business topped out at 60%. These limits shouldn’t be a major issue if you save enough to cover expenses. If you’re combining private and employer policies, you can maximize your coverage. But still, private insurers look at your existing coverage. Don’t expect 100% protection.
Expect the coverage to cost up to 4% of your salary, according to New York Life. If you opt for less coverage, like 50% of your income, you might pay just 1% or 2%. I don’t work in a high-risk job, so I felt OK going with less coverage to save some money.
Save Aggressively While You Can
If you’re fortunate, your employer has been chipping in for your retirement. Many union tradespeople, air traffic controllers, and athletes get pensions, for example. But self-employed workers usually have to handle it all themselves. Plus, pensions and retirement accounts often aren’t accessible without penalty until you’re closer to normal retirement age.
Whether you’re an employee or a contractor in a high-risk job, you need to be saving aggressively while you’re still earning good money. How much you need for financial independence and how much to save monthly will vary. If you’re an athlete who expects to retire at 32, you’ll need to save much more than a plumber who lasts in the job until age 55. The same goes if your expenses are high versus if you’re a frugal person.
Because your situation is unique, you should ask a financial advisor or use a retirement calculator like this Vanguard one. I suggest running the numbers for different retirement ages, including earlier-than-planned ones. Adding a bit to your estimated expenses is also helpful. And when entering the savings rate, go much higher than the usual 10% to 15%. Many people aiming for financial independence are saving at least half their income.
I tried Vanguard’s retirement calculator to get some numbers for a 25-year-old who would retire at 55. If they earn $60,000 and save half of that each year, they’d end up with enough to cover almost $4,100 per month in expenses. Saving just 33% cuts that amount to around $2,700 per month at retirement. So the savings rate matters substantially. Don’t forget to account for other savings, pensions, or Social Security you’ll eventually receive.
You’ll also need to save money in the right places. An employer’s plan is a good start, especially if they’re contributing. Roth and traditional IRAs are common among the self-employed in high-risk jobs, along with solo 401(k)s. These plans might save you on taxes, so check the benefits. I also recommend keeping some money more accessible. You might want to contribute some money to a brokerage account to avoid penalties from early retirement plan withdrawals.
Get Serious About an Early Transition Plan
Don’t wait to figure the next steps out until an injury or something else forces you to retire early. Start several years before you expect to leave your high-risk occupation. Look at your skills and see how you can use those elsewhere to make money. Making extra income while still working your main job can also make it easier to become financially independent.
Think hard about what work you’d like to move into. This might be a direct connection to your high-risk occupation. Many athletes go into coaching and teaching, while others might be spokespeople or write about sports. Tradespeople might do similar work and teach people their skills. They could also consider inspecting homes or doing admin work.
It’s OK to plan to do completely different work after years of stress. You might think up a business idea or make a drastic change, like going from firefighter to part-time accountant. If your transition will require new education, plan for this early on. A retiring athlete who wants to become a high school math teacher would likely need to get state certification, for instance.
Scaling back should also be in the plans. If all goes well, you’ll have enough savings so that this change isn’t too drastic. But you may need to learn to get by on less money and give up some luxuries. A lot of uncertainty also comes with relying on investments for a much longer time than the usual retiree (20-30 years). U.S. Bank says to run stress tests to make sure your money can last after the transition.
Ultimately, achieving financial independence as a high-risk professional can be complex. I recommend bringing in financial professionals. You don’t want to overlook small details that matter. A financial advisor can also advise on the right investments. Use this guide to get started, but let an expert sort out the specifics.
FAQs
Does the 25x rule still work if I’ll retire early from my high-risk job?
That rule assumes you’re withdrawing 4% from your retirement savings over about 30 years. Someone retiring in their 30s or 40s could very well come up short. You also have to consider other income sources you’ll have and how much you’ll spend. Using a retirement savings calculator or letting an advisor run projections is smart.
Does Coast FIRE make sense for people in high-risk occupations?
Since Coast FIRE involves saving enough to reach your retirement savings goal early on, it’s smart for high-risk occupations. Once you reach Coast FIRE, you wouldn’t have to worry about contributions anymore. You could take on less stressful work without having to cut spending drastically elsewhere.
How does estate planning fit into financial independence for high-risk professionals?
On one hand, it can help protect the money you’ve saved over the years. It’s also useful for clarifying who gets your assets if you pass away. Estate planning is complex, though. Ask a professional about things like trusts, powers of attorney, wills, and life insurance.
Our articles provide information purely for educational purposes and do not constitute financial, tax or investment advice. You should always consult with professionals like licensed financial advisors or accountants before making any decisions. We aim to provide up-to-date and accurate information, but we make no guarantees regarding the accuracy or completeness of any content. All our examples are provided for illustrative purposes and may not reflect your personal results. We are not liable for any losses or damages arising from your reliance on the information provided.
Sources:
- https://www.allianzlife.com/about/newsroom/2026-Press-Releases/Many-Americans-Retire-Earlier-Than-Planned
- https://www.empower.com/the-currency/life/what-is-the-average-retirement-age
- https://academic.oup.com/jrssig/article/21/3/6/7686552?login=false
- https://www.bls.gov/charts/census-of-fatal-occupational-injuries/rate-and-number-of-fatal-work-injuries-in-selected-occupations.htm
- https://ablemkr.com/ultimate-guide-financial-planning-tradespeople/
- https://www.farther.com/foundations/financial-planning-for-professional-athletes-best-practices
- https://www.newyorklife.com/articles/cost-of-disability-insurance
- https://www.edelmanfinancialengines.com/education/retirement/saving-for-retirement-high-risk-job/
- https://investors.corebridgefinancial.com/news/news-details/2026/6-in-10-Americans-Struggle-to-Make-and-Act-on-Financial-Decisions-New-Corebridge-Financial-Study-Finds/default.aspx
- https://heritagelegal.com/estate-planning/high-risk-jobs-and-estate-planning/
- https://www.diversifiedquotes.com/high-risk-disability-insurance-coverage-options-for-those-with-medical-challenges/
- https://www.guardianlife.com/disability-insurance/how-much-do-i-need
- https://www.ameriprise.com/financial-goals-priorities/retirement/how-to-retire-early
- https://www.troweprice.com/en/us/insights/six-steps-to-achieve-financial-independence-and-retire-early
- https://investor.vanguard.com/tools-calculators/retirement-income-calculator
- https://www.usbank.com/wealth-management/financial-perspectives/financial-planning/financial-planning-for-athletes.html
